
Ask ten people what will happen if Gen Z stops buying homes and nine will predict the same outcome: the market crashes, real estate collapses, and panic follows. The reality is more nuanced. The sharper question is not whether Gen Z will need housing—they will—but whether they will own it, rent it, or inherit it. Each path channels money through the economy differently, and the consequences for growth, employment and financial stability are significant.
Housing Demand Is Not Disappearing
Economists point out that housing demand is fundamentally driven by population growth and urbanisation rather than generational preference alone. Gen Z will still require a place to live. That place may be inherited, rented or eventually purchased. It is unrealistic to assume that every parent can leave a house for every child. Inheritance will cover only a fraction of the cohort. The rest will either rent or buy, or move between the two over a lifetime.
This distinction matters. A generation that rents rather than buys still generates economic activity—through rental payments, property management, maintenance and related services—but the money flows to landlords and service providers rather than into bank mortgage books or developer balance sheets in the same volume.
Real Estate’s Weight in the Economy
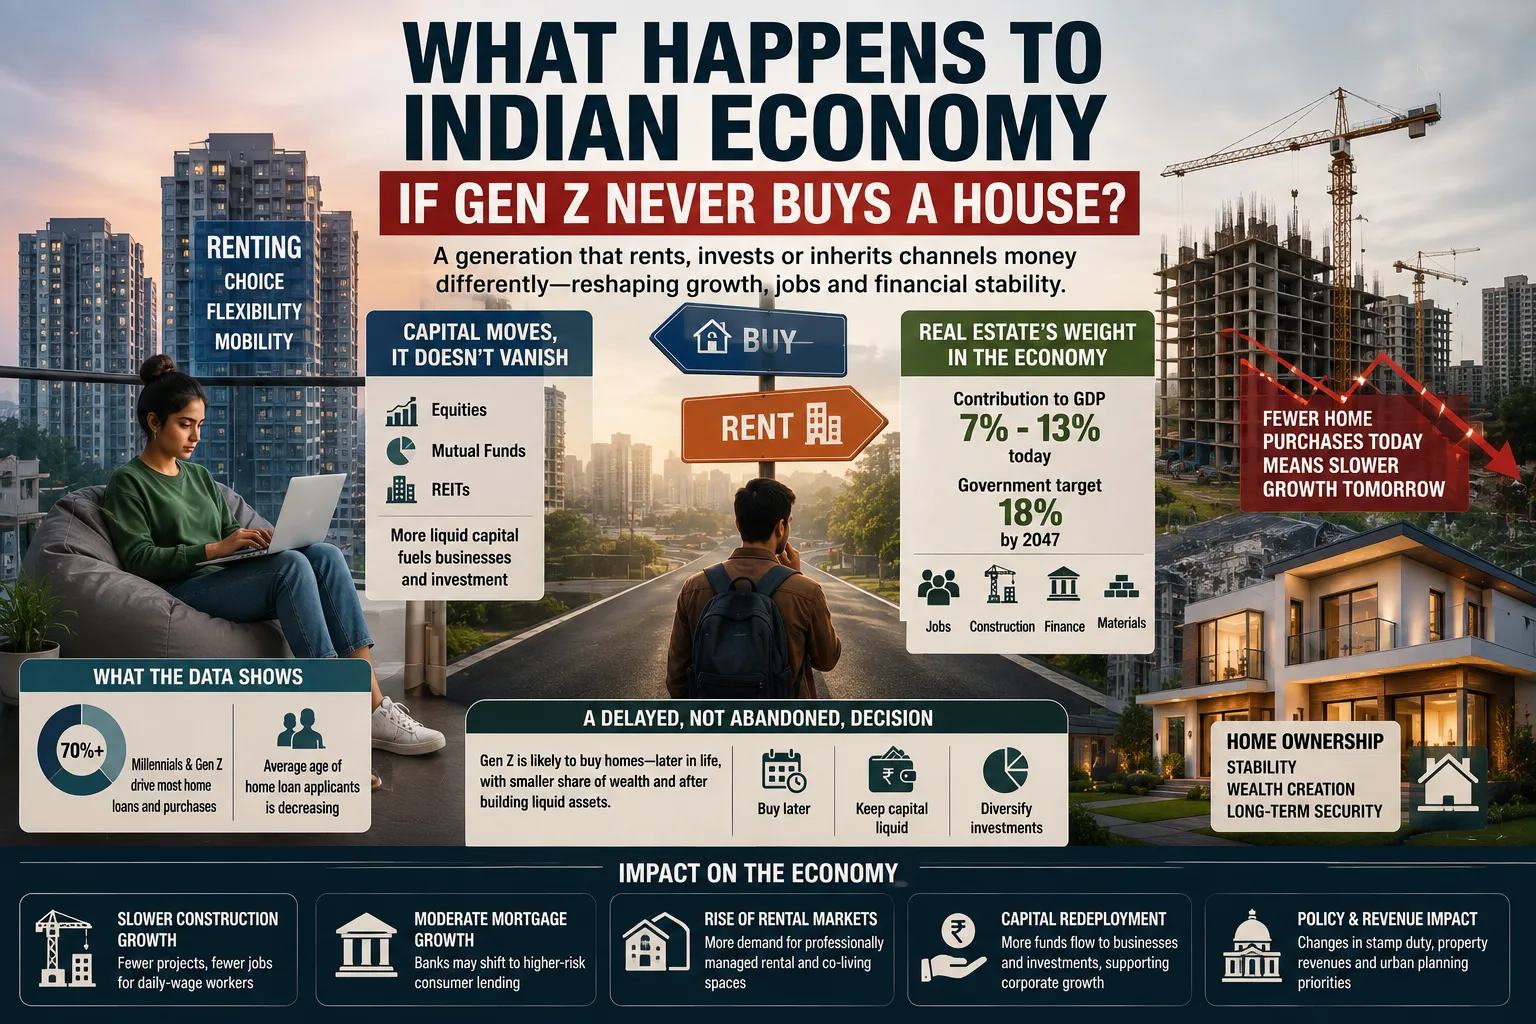
Real estate is not a peripheral sector. Estimates place its contribution to India’s GDP between 7 and 13 per cent today, with the government aiming to raise that share to 18 per cent by 2047. Construction, materials, finance, legal services and a large informal labour force are all tied to the pace of new housing activity. A sustained slowdown in end-user purchases would therefore be felt beyond the price of apartments in metros.
Fewer bookings today typically translate into fewer new project launches tomorrow. Daily-wage workers in construction feel the impact first. Home loans, traditionally one of the safest categories of bank lending, would grow more slowly. Capital that would have gone into long-term housing finance may migrate toward other forms of credit—personal loans, credit cards or buy-now-pay-later products—which carry higher risk profiles for the financial system.
Capital Does Not Vanish; It Moves
There is an important counterpoint. If younger buyers delay the traditional down-payment-and-EMI path and instead channel savings into equities, mutual funds or real-estate investment trusts, that capital does not disappear. It becomes more liquid funding available to Indian companies for expansion and investment. In that sense, a shift away from early, highly leveraged homeownership could redirect household savings toward more productive corporate uses, at least in the medium term.
The trade-off is one of timing and form. Ownership concentrates wealth in a single, illiquid asset that historically has delivered both shelter and appreciation. Renting plus financial assets spreads exposure and preserves mobility, but leaves households more exposed to rental inflation and without the forced-savings discipline of an EMI.
What the Data Actually Shows
Current evidence does not support the idea that Gen Z has abandoned homeownership. Surveys and lending data indicate that millennials and Gen Z together already account for the large majority of residential purchases and home-loan demand. In some reports the average age of home-loan applicants has fallen, not risen. At the same time, a clear segment of urban professionals—sometimes called “almost buyers”—is financially capable of purchasing yet deliberately chooses to rent for longer. Flexibility, career mobility and the desire to keep capital liquid rank high among their reasons.
Affordability pressures reinforce the trend. In several major cities the ratio of EMI to equivalent rent has widened substantially over recent years. When the monthly cost of owning far exceeds the cost of renting the same property, the economic case for early purchase weakens, even for those who still aspire to own later.
Longer-Term Structural Questions
A prolonged preference for renting among a large cohort would gradually alter the structure of the housing market. Developers and investors would need to respond with more professionally managed rental stock, including co-living and institutional rental housing. State governments that rely on property-related revenues and stamp-duty collections would face a different growth trajectory. The traditional “pass-the-parcel” model of continuous price appreciation, dependent on successive waves of new buyers, would face greater pressure if fewer households enter ownership at the same life stage as previous generations.
Lower urban fertility rates, already visible in several large cities, add another layer. Smaller family sizes reduce the automatic demand for larger homes and may further support renting among dual-income, child-free or single-person households.
A Delayed, Not Abandoned, Decision
The most realistic outlook is neither collapse nor business as usual. Gen Z is likely to buy homes, but later in life, with a smaller share of total net worth committed to a single property, and after building more liquid financial assets. Housing demand itself will continue because population and urbanisation continue. What changes is the sequencing of the decision and the channels through which money circulates.
For the economy the implications are gradual rather than catastrophic. Construction and mortgage growth may moderate. Household balance sheets may become less real-estate-heavy and more diversified. Rental markets and related services should expand. Policymakers and the industry will need to adapt—by supporting affordable supply, strengthening rental frameworks and ensuring that delayed ownership does not simply translate into permanent exclusion from asset ownership for large sections of the urban workforce.
The fear that Gen Z will never buy a house overstates the risk. The more accurate observation is that they are rewriting the timeline and the financial logic of that purchase. How the rest of the economy adjusts to that rewrite will determine whether the shift proves disruptive or merely evolutionary.
Read more – morecai.com